Temporary Wage Subsidy Scheme - Operational Stage
Resolution
 TIP: The Temporary Wage Subsidy Scheme closed on 31 August 2020. It was replaced by the Employment Wage Subsidy Scheme (EWSS).
From 4 May to 31 August 2020 the operation of the Wage Subsidy Scheme will still ensure that the subsidy paid to an employer will be based on each individual employee’s average net weekly pay, subject to a maximum weekly tax-free amount.
TIP: The scheme closes for new applications from employers from 31 July 2020.
From 4th May to 31 August 2020, the subsidies will be calculated as follows:
| Employee earnings | Approximate annual salary | Subsidy |
| Employees who earn up to €412 net per week | Up to €24,400 gross per year | A maximum subsidy of 85% of the employee’s net weekly wage (capped at €350 per week) |
| Employees who earn between €412 and €500 net per week | €24,440 - €31,000 gross per year | A maximum subsidy of 70% of the employee’s net weekly wage (capped at €350 per week) |
| Employees who earn between €500 and €586 net per week | €31,000 - €38,000 gross per year | A maximum subsidy of 70% of the employee’s net weekly wage (capped at a maximum of €410 per week) |
| Employees who earn between €586 and €960 net per week | €38,000-€76,000 gross per year | A tiered arrangement will apply and the maximum subsidy payable will be €350 per week. This tiered approach takes into account both the amount normally paid by the employer and the level of reduction in pay borne by the employee, as follows: Gross salary after reduction Subsidy Up to 60% of employee’s previous average Revenue net weekly pay Up to €350 per week Between 60% and 80% of employee’s previous average Revenue net weekly pay Up to €205 per week Over 80% of employee’s previous average Revenue net weekly pay No subsidy payable |
| Employees who earn in excess of €960 net per week | Above €76,000 gross per year | No subsidy is available, unless their gross post-COVID-19 income has fallen below €960 per week. In those cases, the tiered arrangement applicable to incomes in excess of €586 per week (approx €38,000 gross per year) will apply. |
| Employees where earnings have been reduced to below €960 net pay a week, and the reduction is more than 20% of their normal pay | Above €76,000 gross per year | A subsidy of up to €205 is available. If the reduction was more than 40%, a subsidy of up to €350 is available. To calculate the level of subsidy payable, current gross pay will be compared with previous average net weekly pay for January and February 2020. |
Tapering
Tapering is applied when the gross pay paid by the employer and the subsidy exceed the employee’s previous average net weekly pay.
If you top up payments by more than the permitted amount, the subsidy will be tapered – for every €1 extra paid, €1 will be taken from the subsidy. This is to ensure that no employee is better off under the Wage Subsidy Scheme.
TIP: If tapering is applied to your payments, the refund you receive will be less than the subsidy you have paid.
Downloading the CSV for the operational phase
The revenue has issued a CSV file containing the Average Net Weekly Wage for each eligible employee on your payroll. You can download this from your ROS account.
- From within your Revenue account, go to the My Services tab.
- Within the Employer Services section, click Request RPNs.
- From the end of the page, click Request Temporary Wage Subsidy Scheme calculation, then Request Calculation.
- Enter your Revenue password, then click Sign & Submit.
The calcuation CSV will then download.
 NOTE: Note: You cannot import the CSV directly into Payroll.
Processing employees in your payroll
Enter the following details for eligible employees when running their payroll:
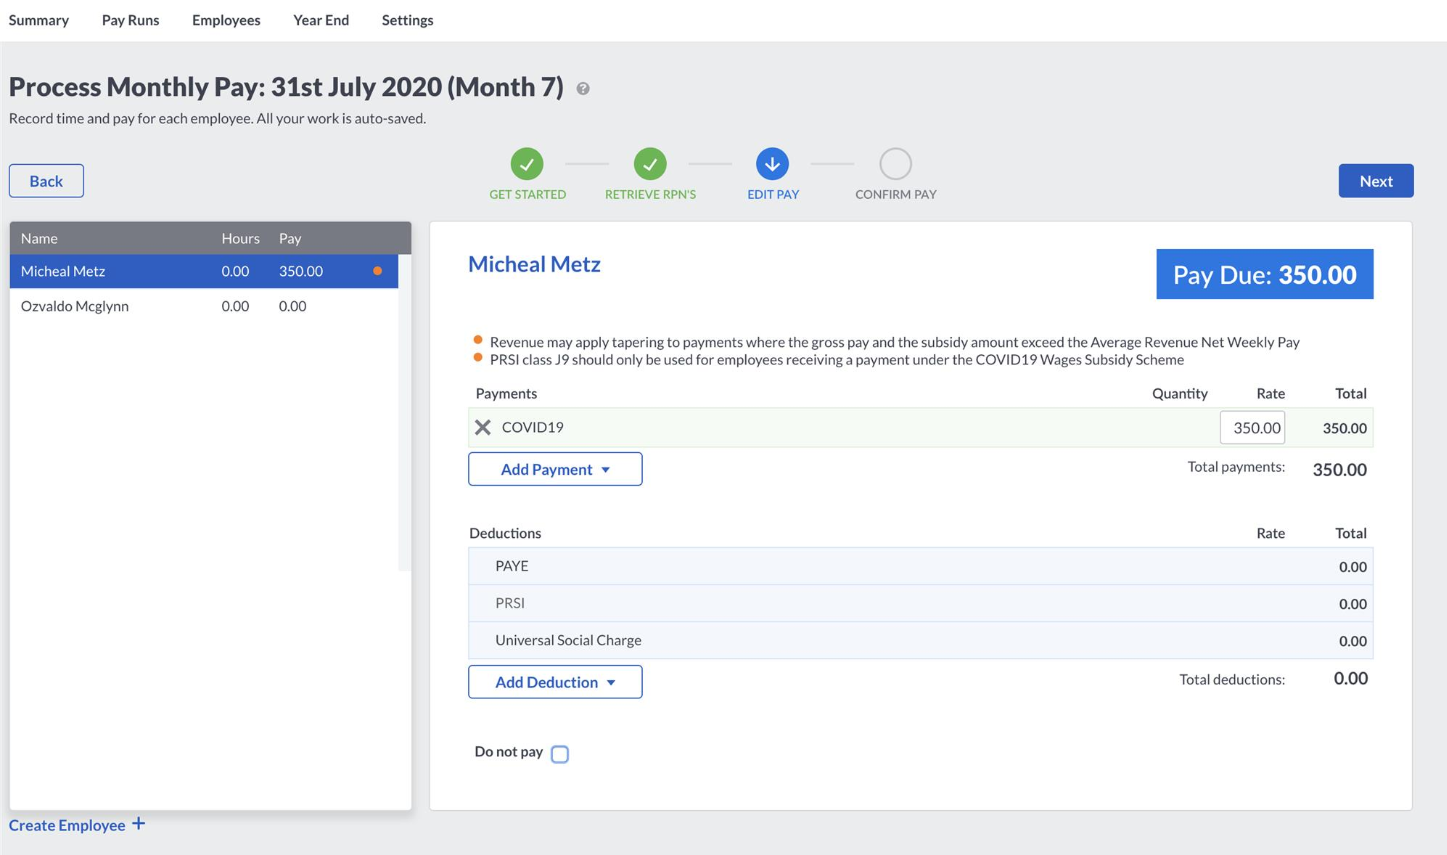
Set employee's PRSI Class to J9.
TIP: If you haven't already set this in their employee record, you can edit the PRSI class within the pay run by clicking the employee name. Enter the wage subsidy amount as non-taxable amount.
For eligible employees, the maximum weekly wage subsidy amount payable as calculated by Revenue is available in the CSV file you downloaded.
Be careful not to include the Temporary Wage Subsidy payment in Gross Pay. If the subsidy figure is included in the gross pay, it will be treated as Additional Gross Pay. Revenue will apply tapering and the employer refund amount will be reduced accordingly.
If you aren't making any additional gross payments to your employee, you must include a pay amount of €0.01 in Gross Pay. This is to trigger a payroll submission request.
If you are making an additional gross payment to your employee, include this amount in the Gross Pay. The value of the Gross Pay in conjunction with the maximum weekly wage subsidy determines the amount of subsidy that is payable.
TIP: The Temporary Wage Subsidy Scheme ends on 31 August 2020. You cannot claim for pay runs dated after this point.
A Sample Calculator to help calculate the wage subsidy is available on the Revenue website.
Related articles
Reconciling Temporary Wage Subsidy Scheme Payments
Disclaimer
This article provides general rather than specific guidance to assist all of our customers. We always do our best to make sure that the information is correct but as it's general guidance, no guarantees can be made concerning its suitability for your particular needs. The information is valid at the time of publishing and is provided without any warranty of any kind, express or implied. You should take professional advice if you require specific guidance on your individual circumstances, for example to ensure that the results obtained from using our software comply with statutory or regulatory requirements. For Employers, PAYE, PRSI and general tax enquiries you should call Revenue of Ireland (ROS) National Employer Helpline on 01 738 36380 or visit their website at Revenue Online In no event will we be liable to you for any direct, indirect, consequential or incidental loss or damage arising out of or in connection with your use of the information provided.
Solution Properties
- Solution ID
- 222001000101398
- Last Modified Date
- Tue Jun 20 13:54:46 UTC 2023
- Views
- 0